Exports of goods from Israel are normally zero-rated, while exported services qualify for the zero rate only when the statutory conditions in Section 30 are met and no Israeli party benefits from the service. Foreign businesses that operate in Israel must register and appoint a fiscal representative within 30 days of starting activity, following the VAT registration requirements that provide practical guidance on local registration processes.
TL;DR:
- Exported goods qualify for zero VAT when shipped out of Israel with proper customs documentation, but exported services require strict proof of no Israeli beneficiary.
- Foreign businesses operating in Israel must register and appoint a local fiscal representative within 30 days of starting activity to comply with VAT rules.
- Services to non-residents can only qualify for zero rate if no Israeli party benefits, with conference-related services meeting specific criteria such as attracting at least 50 foreign tourists.
- Invoices over NIS 15,000 in 2026 must include an allocation number for input tax deduction, making early registration and proper documentation essential.
- Common audit triggers include mixing Israeli and foreign beneficiaries in contracts, missing proof of service use, and incomplete documentation; proactive record keeping simplifies compliance.
Which transactions count as taking place in Israel
Israeli VAT law starts from a simple question: did the transaction happen in Israel? Sections 2 and 14 through 16 of the VAT Law answer that differently for goods and services. A sale of goods is generally taxed where the goods are located at the time of delivery. A service is taxed based on where it is actually rendered or, for many commercial services, where the recipient is a resident.
A few factors tend to decide the classification:
- The physical location of goods at the point of transfer.
- The tax residency of the service recipient.
- Whether the supplier has a branch, agent, or other fixed presence in Israel.
A foreign company selling through an Israeli agent, for example, may find that the agent’s presence pulls the transaction into Israeli VAT scope even though the foreign company itself has no office here.
When Section 30 allows a zero VAT rate
The main categories are:
- Exports of goods shipped out of Israel to a foreign buyer.
- Defined services supplied to non-resident recipients who have no Israeli beneficiary.
- Certain services tied to international conferences held in Israel.
A 0% rate is not the same as a VAT exemption. Under the VAT Law, an exporter charges no output tax on the sale but still deducts input VAT on related costs, which is a meaningfully better outcome than an exemption that blocks input deduction entirely. Exported goods tend to be the easier case because shipping and customs paperwork does much of the proof work. Exported services carry a heavier evidentiary burden, since there is no physical border crossing to document, and the Israel Tax Authority reviews these claims closely.
Services to non-residents and the conference rule
The core test for zero-rating a service is whether any Israeli party benefits from it, even indirectly. Based on the VAT Law, the Tax Authority applies this “no Israeli beneficiary” condition strictly: a contract that looks like a pure export on paper can fail the test if an Israeli subsidiary, partner, or end user gets any practical advantage from the work.
Conference-related services get their own interpretive ruling. According to Parsanut 14/2018, services supplied to international organizations for holding a conference in Israel may qualify for 0% when specific conditions are satisfied:
- The conference draws at least 50 foreign tourists.
- The services fall within the ruling’s defined list of eligible activities, such as conference production, translation, and related advertising.
- The organizer keeps records tying the service to the qualifying event.
Catering and accommodation for conference attendees generally fall outside this 0% treatment, even when everything else about the event qualifies.
Registration rules for foreign businesses operating here
Under Section 60 of the VAT Law, a foreign resident carrying on business activity in Israel must register as a taxable dealer and appoint a local fiscal representative within 30 days of starting that activity. This applies whether the activity is a short-term project or an ongoing commercial presence.
Practical steps for most foreign businesses look like this:
- Engage a fiscal representative resident in Israel who can file on the company’s behalf.
- Register the business with the relevant VAT office before invoicing begins.
- Set up invoicing that reflects the correct VAT treatment from the first transaction, since retroactive fixes are harder and slower than getting it right at the start.
Registration also determines whether reverse-charge rules apply to certain inbound services and affects what penalties the Tax Authority can impose for late or missing filings.
Pro Tip: Appoint your fiscal representative before you sign your first Israeli contract, not after your first invoice is rejected.
What documentation an auditor expects to see
For goods, auditors want export declarations, shipping and delivery records, and payment evidence from the foreign buyer. For services, they look for signed recipient declarations, contracts that specify where the service is used, and, for conferences, attendee lists or passport data supporting the foreign-tourist count.
- Keep export documentation (shipping and customs records) tied directly to each invoice.
- Retain signed contracts that state the place of use and the identity of the beneficiary.
- Hold proof of remote consumption for digital or intangible services.
Incomplete files are the most common reason a 0% claim gets reclassified during an audit, and businesses should retain these records for as long as the Tax Authority can reopen the relevant tax year.
The invoice allocation number and 2026 rules
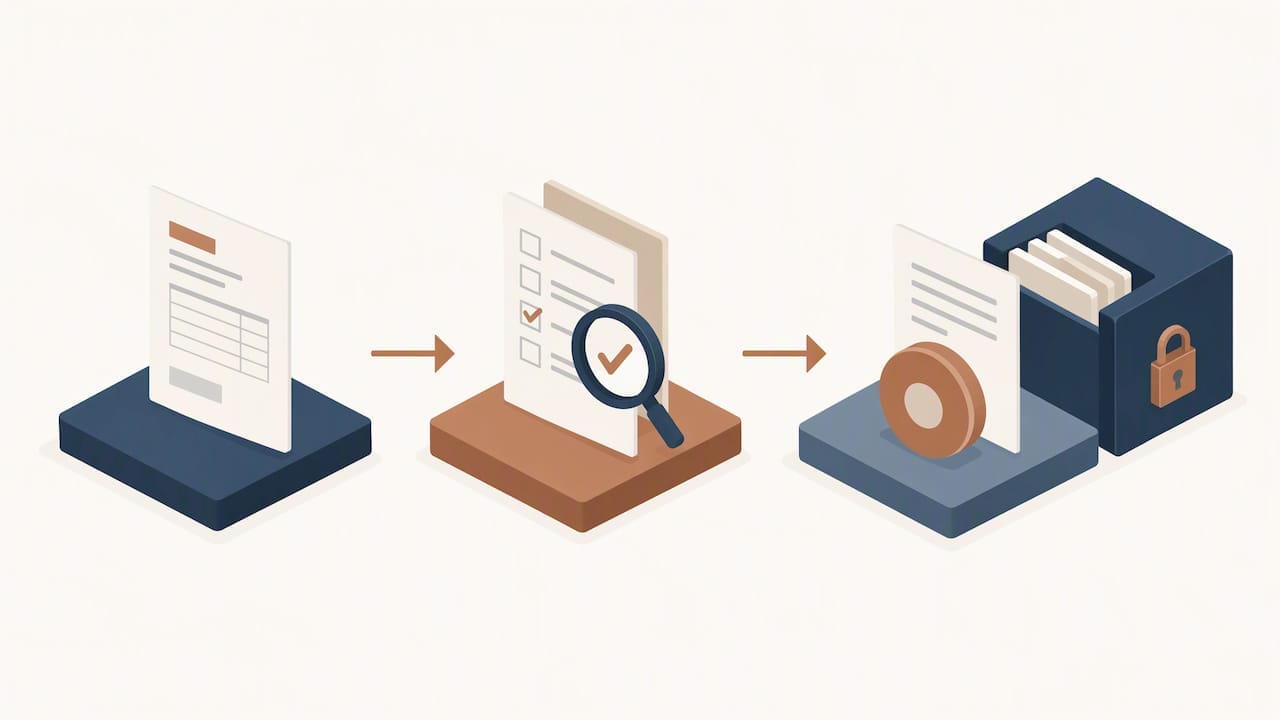
Israel’s invoice allocation system ties input tax deduction to a number issued by the Tax Authority for each qualifying invoice. Without that number, a buyer may not be able to deduct the VAT shown on the invoice at all.
For 2026, invoices with a pre-VAT value above NIS 15,000 typically require an allocation number, according to the Israel Invoice Model guidance, which makes API integration with the Tax Authority’s system a practical necessity for businesses issuing invoices at that scale.
- Continue holding an invoice without an allocation number only as a short-term stopgap, since the deduction stays at risk.
- Request a reversal and apply reverse-charge treatment where that fits the transaction.
- Ask for a hearing with the Tax Authority when a legitimate invoice is denied an allocation number in error.
Common audit triggers and how to lower your risk
Most 0% denials trace back to a handful of patterns: contracts that mix Israeli and foreign beneficiaries, missing proof of delivery or use, and invoices that lack required details or an allocation number.
- Keep export contracts and domestic contracts in separate files and invoicing lines.
- Collect a signed confirmation from each foreign recipient about where and how the service is used.
- Build a standing export-proof file you update with every transaction, not just before a filing deadline.
Pro Tip: When a deal structure is genuinely ambiguous, a pre-ruling request to the Tax Authority is often cheaper than defending the position after an audit begins.
A working checklist for cross-border VAT compliance
Most businesses that get this right follow a consistent sequence rather than treating each transaction as a one-off:
- Classify the transaction as goods or services and identify where it legally takes place.
- Confirm the place-of-supply analysis under Sections 14 through 16.
- Choose the VAT treatment: standard rate, 0% export, or reverse charge.
- Gather the documentation that supports that treatment before issuing the invoice.
- Issue the invoice with an allocation number when the value requires one.
- File the transaction in an audit-ready folder, tagged by customer type.
Mixed contracts, where one agreement covers both an Israeli and a foreign component, need separate VAT treatment for each piece rather than a single blended rate. Keep template contracts and invoice formats on hand so each new deal does not require rebuilding the documentation approach from scratch.
When a cross-border VAT issue needs a lawyer, not just an accountant
Our firm focuses on Israeli law for clients operating from abroad, and we represent overseas businesses remotely without requiring them to travel to Israel. Some situations call for legal review rather than bookkeeping: service bundles that mix taxable and zero-rated elements, group structures spanning Israel and other countries, disputes over conference eligibility, or defending a position once the Tax Authority opens an audit.
— Menora Law
We work with international businesses on VAT registration, fiscal representative appointments, audit defense, and contract and invoice review for Israeli transactions. When your company sells into Israel or operates here through a branch or agent, getting the classification right from the first contract saves far more time than correcting it later.
Before an initial consultation, gather your relevant contracts, recent invoices, and any correspondence you have already had with the Tax Authority. We also advise on broader cross-border matters, from company structuring to real estate and intellectual property, for clients based overseas. Visit the Menora Wet site to arrange a consultation on your specific transaction or filing question.
This article is general information, not a substitute for advice from a qualified lawyer. Consult a qualified legal professional about your own circumstances before acting on anything here.
FAQ
What does “מע"מ אזור אישי” mean for a business?
The personal VAT area refers to the Tax Authority’s online portal where registered dealers manage filings, invoices, and allocation numbers. Foreign businesses registered under Section 60 typically access this through their appointed fiscal representative.
What is the VAT rate table and which rate applies to exports?
The standard Israeli VAT rate applies to most domestic transactions, while qualifying exports of goods and certain services to non-residents are taxed at 0% under Section 30. The applicable rate depends on classification, not on the type of business alone.
What is the VAT Law and where does it come from?
The VAT Law is Israel’s governing statute for value added tax, covering registration, taxable transactions, zero-rating, and enforcement. The current framework, including the export and registration provisions discussed here, is published on the Israel Tax Authority’s site.
Is there a tax treaty between Israel and other countries that affects VAT?
Israel’s bilateral tax treaties generally address income tax rather than VAT, so a treaty with another country typically does not change VAT treatment on a cross-border sale. VAT classification instead depends on the place-of-supply rules and Section 30 conditions described above.
Does VAT apply to imports and digital services sold into Israel?
Imports of goods are generally subject to VAT at the border alongside customs duties, while foreign suppliers of digital services to Israeli customers may face registration or reverse-charge obligations depending on the buyer’s status. Each case depends on the specific facts, so a review of the transaction structure is worth doing before assuming a treatment applies.
 English
 Afrikaans
 العربية
 বাংলা
 Čeština
 简体中文
 Nederlands
 Suomi
 Français
 Deutsch
 עִבְרִית
 हिन्दी
 Magyar
 Italiano
 日本語
 한국어
 Polski
 فارسی
 Português do Brasil
 Русский
 Español de México
 Українська